
Lei Lithium Project
On this page:
- Key Points
- Water Use and Management
- Jobs and Local Business Opportunities
- Aboriginal Cultural Heritage and Participation
- Dust, Noise and Visual Amenity
- Traffic and Road Safety
- Rehabilitation and Closure
- Project Timeline
- Mineral Resource
- Scoping Study
- Scoping Study Webinar
- FAQs
- Feedback
- Subscribe to Project Updates
Lithium Plus Minerals (LPM) is planning a small underground lithium mine at the Lei Deposit, part of its Bynoe Lithium Project, located on the Cox Peninsula south-west of Darwin near other operating lithium mines.
If approved, lithium ore from the mine would be crushed and screened on site, then trucked to Darwin Port via existing roads for export with no chemical processing of lithium proposed on-site.
Lithium is used in rechargeable batteries for electric vehicles, renewable energy storage, mobile phones and other technologies that support cleaner energy.
LPM has advanced the Lei Lithium Deposit through the Northern Territory (NT) environmental approval process and has completed a Scoping Study that supports progression of Lei to a Pre-Feasibility Study (PFS).
The NT Government requested additional information via a Supplementary Environmental Report (SER), which the Company lodged in September 2026 with approval targeted for Q1 CY2027, completing the principal assessment and enabling the environmental (mining) licence application.
A 20-year Mining Lease has been granted for the proposed mine, however, environmental and other approvals, including an Authority Certificate from the Aboriginal Areas Protection Authority, are needed before mining can start.

Small Underground Mine
20-Year Mining Lease
80-110 Mining Jobs
No Chemical Processing
The proposed Lei Lithium Project will involve:
- Construction of a small underground lithium mine targeting spodumene (lithium ore).
- Construction of a cut-and-cover tunnel to access the orebody.
- Underground mining using drill-and-blast methods.
- Transfer of mined ore to a surface run-of-mine pad adjacent to the tunnel entry for stockpiling and feeding ore to the crusher.
- Crushing and screening of ore to produce Direct Shipping Ore (DSO), with no lithium processing plant or tailings storage facility proposed on site.
- Construction and operation of a temporary waste rock stockpile before backfilling underground, leading up to mine closure.
- Construction of site infrastructure, including administration offices, crib rooms, workshops, fuel storage, laydown areas, explosives storage, ventilation infrastructure, internal haul roads, light vehicle roads and stockpile areas.
- Development of water management infrastructure to manage clean runoff and mine-affected water.
- Construction and use of site access roads and haul roads connecting the mine to the regional road network.
- Transport of spodumene (lithium ore) from the mine site to East Arm Wharf at Darwin Port during daylight hours using road trains on existing roads.
- Operation of a haulage route via Fog Bay Road, Cox Peninsula Road, Stuart Highway, Tiger Brennan Drive and Berrimah Road to East Arm Wharf.
- Progressive mine closure and rehabilitation work, including backfilling mine waste underground, removal of infrastructure, and rehabilitation of disturbed land.

Water Use and Management
The Lei Lithium Project is expected to use less water than some other mining projects because it does not plan to process lithium on-site.
Water will mainly be used for:
- Underground mining
- Dust control
- Washing mine vehicles and trucks
- Site amenities and administration facilities
The mine is expected to meet its own operational water needs, except during extreme drought. Drinking water and water for office use would be delivered to the site by tanker.
Any release of water from the site would only happen under an approved licence and only when water quality requirements are met.
A Water Management Plan will be implemented to guide the separation and management of clean stormwater, mine-affected water, and operational water to protect downstream environments, surface water flows, and groundwater values.
Jobs and Local Business Opportunities
The Lei Lithium Project will create approximately 120–150 construction jobs and around 80–110 operational mining jobs with most work at the mine carried out by specialist construction and mining contractors.
LPM will seek to provide early visibility of upcoming work packages where practicable and encourage contractors to identify opportunities for local businesses, suppliers and workers.
The workforce is expected to live locally or in the surrounding area with no on-site accommodation camp proposed. Bus transport is expected to be provided for workers travelling to and from Palmerston, with pick-up points along the route.
Aboriginal Cultural Heritage and Participation
Cultural heritage surveys and assessments have been conducted in full alignment with NT Aboriginal cultural heritage governing legislation, and form part of the SER. This process helps to identify any sites of significance within the Project footprint, informing mine planning and infrastructure layout. LPM will apply to the Aboriginal Areas Protection Authority for an Authority Certificate before any project works begin.
LPM is committed to working with Aboriginal employment, training and business organisations to identify practical engagement and participation opportunities for Aboriginal people and businesses.
Dust, Noise and Visual Amenity
The Lei Lithium Mine will be underground, significantly reducing surface disturbance compared with an open-cut mine.
LPM proposes to manage dust, noise and visual impacts by keeping a vegetation buffer along Fog Bay Road, spraying water on dusty roads and work areas, covering truck loads, monitoring dust from site activities and responding to community enquiries and complaints.

Traffic and Road Safety
Lithium ore will be trucked from the mine to East Arm Wharf at Darwin Port using an existing network of established roads already used by road trains. The haulage route will be Fog Bay Road, Cox Peninsula Road, Stuart Highway, Tiger Brennan Drive, and Berrimah Road to East Arm Wharf.
During peak operations, the project is expected to generate about 68 two-way vehicle movements per day, including about 20 heavy vehicle movements. Heavy vehicles will only operate during daylight hours with movements expected to be spread across an operating period between 6:00am and 6:00pm.
A traffic study has been completed. While some sections of the road access to the mine need maintenance, the traffic study found that the existing road network can comfortably handle the extra traffic from the Lei Lithium Project.
To help manage and improve road safety, LPM will:
- Restrict road train movements near Berry Springs Primary School during school drop-off and pick-up times.
- Operate heavy vehicles only during daylight hours.
- Provide bus transport for workers.
- Prepare a Traffic Management Strategy.
- Cover truck loads to minimise dust.
- Reduce haulage speeds in sensitive areas to minimise noise and vibration.
- Notify nearby residents and businesses about the project works.
- Complete a baseline road conditions audit, and regularly monitor road conditions to identify maintenance needs.
Rehabilitation and Closure
LPM will prepare a Mine Closure Plan (MCP) for the Lei Lithium Mine that will explain how disturbed areas will be made safe, stable, and non-polluting after mining is finished.
Closure planning will include removing temporary infrastructure, managing mine openings and waste materials, rehabilitating disturbed land and monitoring water quality, vegetation and land stability.
A concept MCP was submitted as part of the SER. Rehabilitation planning will continue as the project develops.
Project Timeline
Current
- SER has been submitted to the NT Government and is now under assessment.
- Ongoing environmental studies, groundwater investigations and technical assessments.
- Scoping Study completed and PFS in preparation.
- Infill and extensional drilling targeting the deeper Inferred stoping areas and adjacent lithium bearing pegmatites within ML33874 has commenced.
Short Term
- Approvals for SER targeted for the first quarter of 2027, allowing for submission of the environmental (mining) licence application.
- PFS scheduled for completion in the second quarter of 2027.
- Final Investment Decision (FID) subject to completion of PFS.
- Project funding expected to be secured by mid-2027.
Future Development
- Site establishment and mine construction commencement subject to receipt of environmental and other approvals.
- First delivery of material to the Run of Mine (ROM) targeted in August 2028.
Long Term Planning
- Continual review and development of the MCP and progressive closure and rehabilitation of disturbed areas, where possible.
- Long-term environmental monitoring and maintenance following mine closure.
Mineral Resource
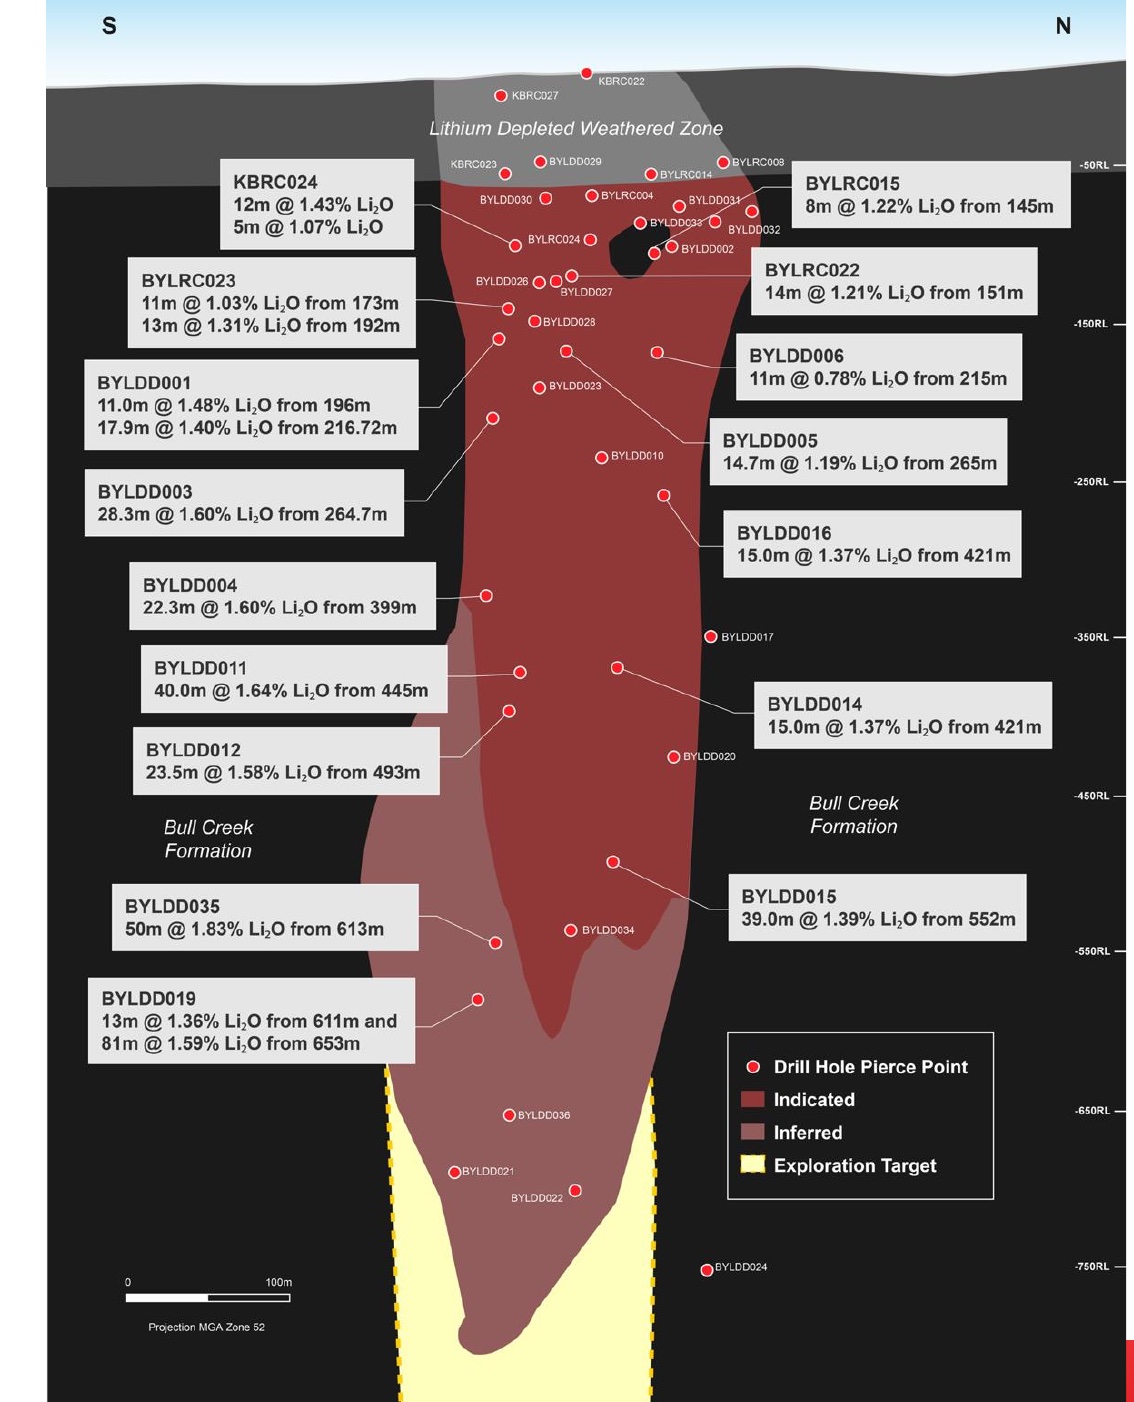
The MRE for the Lei Deposit, as announced on 15 July 2026, is summarised in the table below (at a 0.5% Li2O cutoff):
| Category | Tonnes (Mt) | Li₂O (%) | Contained Li₂O (kt) |
| Indicated | 2.85 | 1.49 | 42.55 |
| Inferred | 2.37 | 1.51 | 35.88 |
| Total | 5.22 | 1.50 | 78.42 |
The current MRE for the Lei primary pegmatite is 5.22Mt at 1.50% Li₂O for 78.42kt of contained Li₂O, superseding the previous December 2023 estimate. The updated MRE represents a 34% increase in contained lithium over the December 2023 maiden estimate and increases the Indicated proportion of the MRE to 54%.
Scoping Study
A Scoping Study was completed in October 2026 for the Lei Lithium Project. The Study highlights the technical and economic potential of a staged development commencing with a low capital intensity Direct Shipping Ore (DSO) operation comprising contract underground mining, on-site crushing and screening, road haulage and export of lithium-bearing pegmatite through Darwin Port.
A$325M
NPV₈% (after tax)
A$87.7M
Project capex
A$492.7M
LOM free cash flow (after tax)
6 years
Mine life
75.4%
IRR (after tax)
A$238/t
AISC of DSO product (delivered CIF China)
48.4kt
LOM contained Li₂O production
1.8 years
Payback period from first production
For the purposes of the Study the Company adopted a DSO price of US$350/t on a 1.5% Li₂O product basis, applied pro-rata to the grade of material delivered in each period, with an AUD/USD exchange rate of 0.70.
| Scenario | US$/t at 1.5% basis | A$/t realised | LOM gross revenue (A$M) | LOM EBITDA (A$M) | NPV₈% pre-tax (A$M) |
| Downside (−20%) | 280 | 366 | 1,290 | 609 | 251 |
| Adopted | 350 | 458 | 1,613 | 907 | 466 |
| Upside (+20%) | 420 | 550 | 1,935 | 1,206 | 682 |
The Study outlined a target mining rate of 750ktpa of mineralised material, crushed and screened on site to a P100 75mm DSO product, delivered by truck to Darwin Port for export. Over a six year mine life (LOM), the Project has a production target of 3.52Mt at 1.37% Li₂O for 48,400t of contained Li₂O (57% Indicated, 43% Inferred).
By adopting a contractor-operated underground mining and mobile crushing model, the Company kept capital intensity low, outlining LOM gross revenue of A$1,613 million and EBITDA of A$907 million, from a project capital of A$87.7 million including a 15% contingency and no required processing plant capital.
The initial capital payback period is 1.8 years from first production with a post-tax NPV₈% of A$325 million, and a post-tax internal rate of return (IRR) of 75.4%. The study also outlined an All-In-Sustaining-Cost (AISC) of A$238 per tonne of DSO product delivered CIF China. The Study suggests high MRE confidence for capital payback with 100% of scheduled production during Years 1 and 2 classified as Indicated Mineral Resources and Indicated material representing 88% of cumulative production through Year 3.
| Key Parameters | Unit | LOM |
| Capital and operating costs | ||
| Project capital (incl. 15% contingency) | A$M | 87.7 |
| Sustaining capital (funded from operating cash flow) | A$M | 129.6 |
| Total capital | A$M | 217.3 |
| Operating cost, excluding royalties | A$/t DSO | 167.9 |
| Operating cost, including royalties | A$/t DSO | 200.3 |
| Project outcomes | ||
| LOM gross revenue | A$M | 1,612.7 |
| LOM EBITDA | A$M | 907.4 |
| NPV₈% (pre-tax, real, ungeared) | A$M | 466.4 |
| IRR (pre-tax, real) | % | 93.6 |
| NPV₈% (post-tax, real, ungeared) | A$M | 325.0 |
| IRR (post-tax, real) | % | 75.4 |
| Payback from start of construction (post-tax) | Years | 2.8 |
| Payback from first production (post-tax) | Years | 1.8 |
| C1 cash cost, CIF China | A$/t DSO | 167.9 |
| All-In Sustaining Cost (AISC), CIF China | A$/t DSO | 237.9 |
| Operating margin on AISC | A$/t DSO | 220.0 |